CPOS: Tap to Pay Card Reader

- 155.00 Reviews
- 4.4
- Downloads
- 10,000+
Our take on CPOS: Tap to Pay Card Reader from Appgk
Turning a phone into a card reader sounds like the kind of idea that either removes a major daily nuisance or creates a new set of small frustrations. After spending time with CPOS: Tap to Pay Card Reader, my view is fairly clear: it is most appealing as a lightweight payment tool for people who need mobility and simplicity, rather than as a complete replacement for a full point-of-sale system. Its strongest quality is the way it aims to keep the payment setup close at hand, while its biggest weakness is that a phone-based reader demands careful attention to device compatibility, connectivity, and the practical limits of a compact business app.
CPOS is a free Business app from CPOS, designed for Android users who want to accept card payments without carrying a separate reader. It is suitable for Everyone, and the current release is version 2.34.0. The app has reached over ten thousand installs and holds a 4.4 average from more than two hundred ratings, which gives it a useful level of real-world visibility without making it feel like an overcomplicated enterprise platform.
What using CPOS feels like in everyday business
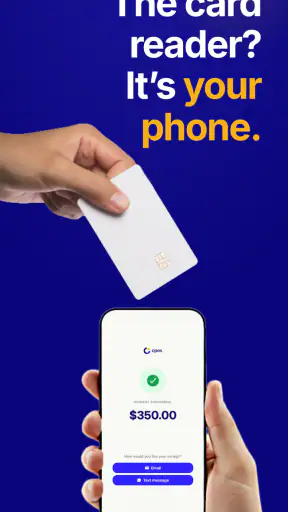
The most convincing use case is a small transaction away from a traditional counter. I can imagine using it at a market stall, during a home visit, at a local class, or while collecting payment after a service. In those situations, carrying a dedicated terminal can feel excessive, especially when the phone is already in my hand. CPOS focuses on that practical gap: the customer presents a card or compatible payment method, and the phone becomes the center of the transaction.
That approach changes the preparation routine. Instead of remembering a phone plus a separate reader, I only need to think about the phone and the payment workflow. This is not just a matter of saving space. Fewer devices also mean fewer batteries to charge, fewer cables to pack, and less chance of leaving an essential accessory behind. For a person who works from different locations, that simplicity can matter more than a long list of advanced business tools.
Best Parts of CPOS: Tap to Pay Card Reader
Things to Keep in Mind About CPOS: Tap to Pay Card Reader
I also like the psychological advantage of a familiar device. A dedicated terminal can look professional, but it can also feel like another piece of equipment that needs explanation. A phone-based setup is easier to keep nearby and easier to incorporate into an existing routine. The important distinction is that CPOS does not magically turn every phone into a universal payment terminal. The phone still needs to be suitable for the task, and the business still needs a reliable process around it.
The strongest benefit is reduced equipment
CPOS makes the most sense when the cost and inconvenience of hardware are the main obstacles. The app is free, and its central proposition avoids the usual monthly equipment burden described for this type of setup. That makes it attractive to someone testing card acceptance for the first time, a seasonal seller who does not want permanent hardware, or a small operator whose payment volume does not justify a larger checkout system.
News and Features Related to CPOS: Tap to Pay Card Reader

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
News
Moovit Review: A More Reliable Way to Navigate Everyday Transit
News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
There is a useful difference between “free to install” and “free in every part of the payment process,” and I would keep that distinction in mind before relying on it for a business. The app itself costs nothing, but card payments can still involve the terms of the payment service, financial institution, or processing arrangement connected to the transaction. I would check those conditions before making CPOS the only way customers can pay. The absence of a monthly app fee is helpful, but it should not be confused with a promise that every transaction is cost-free.
Another strength is the potential for faster setup in temporary situations. Suppose I am selling handmade items at a weekend event. A conventional point-of-sale arrangement may be more than I need, while cash handling creates its own problems with change, counting, and security. A phone-based reader gives me a middle option: I can keep the payment process compact and avoid turning a short event into a full technology project.
Don't want to read the full review?
That same flexibility could help service professionals. A cleaner, tutor, repair worker, photographer, or independent instructor may finish a job somewhere that has no counter or checkout area. In that moment, a phone-based payment tool is more practical than asking the customer to wait until later or send a separate transfer. The value is not flashy functionality; it is reducing the distance between finishing the work and completing the payment.
Where the workflow needs discipline
The best way to use CPOS is to treat it as one part of a payment routine rather than the entire business operation. Before accepting a customer, I would prepare the phone, keep the battery comfortably charged, confirm that the connection is dependable, and make sure the customer can see the amount before approving it. Those steps sound obvious, but they become especially important when the phone is doing the job of a dedicated terminal.
Screenshots
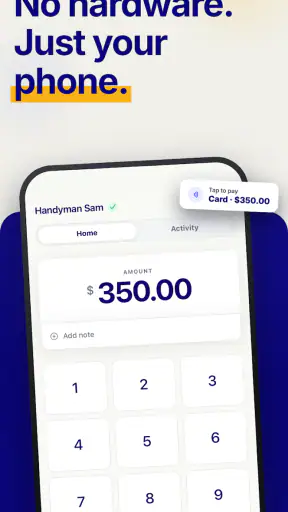
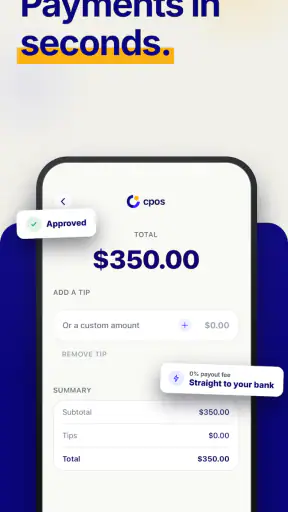
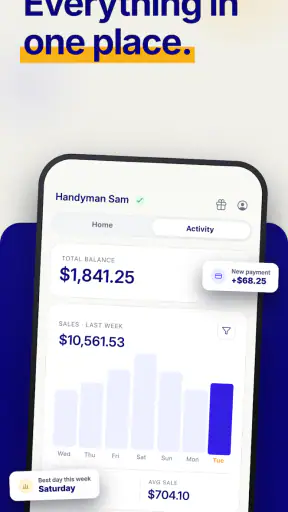
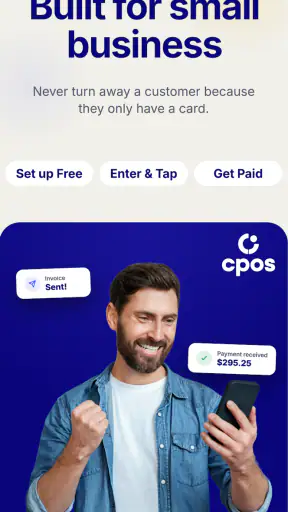
I would also separate payment acceptance from record keeping. A compact card-reader app may be excellent for taking a payment, but that does not automatically mean it replaces invoicing, inventory, appointment management, bookkeeping, or detailed sales reporting. If I were running a small shop with many products, staff members, refunds, stock adjustments, and end-of-day reconciliation, I would compare CPOS carefully with a full point-of-sale package before switching. A phone reader can solve the payment moment while leaving the wider administrative work to another system.
One practical tip is to decide in advance what happens when the phone cannot complete a transaction. At a busy event, a weak connection or an unavailable device can interrupt the queue. I would have a backup payment method ready, whether that means cash, another approved device, or a separate arrangement. This is not a criticism unique to CPOS; it is the trade-off of putting payment acceptance on a general-purpose phone. The convenience is high when everything is ready, but the failure point is concentrated in one device.
What CPOS does better than carrying a reader
The comparison with a traditional card reader is straightforward. A separate terminal usually feels more dedicated and may be easier to hand to a customer without exposing the rest of a phone’s screen. It may also fit better into a permanent counter setup. CPOS has the opposite advantage: it reduces the amount of equipment and makes mobile acceptance more natural.
For occasional sellers, the phone-first approach is less intimidating. There is no need to build the whole operation around a terminal before knowing whether customers will actually use card payments. For mobile workers, it can also be more convenient than moving between a phone and a reader during every transaction. I would choose CPOS over a conventional terminal when portability and low commitment matter more than a dedicated checkout experience.
However, I would not automatically choose it for a busy retail environment. A shop with a steady line of customers may benefit from a larger display, a stable counter setup, receipt handling, staff controls, and more visible transaction management. Those needs can make a traditional point-of-sale system feel calmer and more dependable, even if it costs more or requires additional hardware. CPOS is strongest when the business is small, mobile, or intentionally simple.
Compared with cash and bank transfers
Cash remains easy to understand, but it requires change, secure storage, and manual counting. A phone-based card payment can reduce those chores and make the customer experience more direct. It is especially useful when the exact amount matters and I do not want to carry a float. On the other hand, cash does not depend on a charged phone or a working connection, so I would not discard it completely for outdoor events or locations where service quality is uncertain.
Bank transfers can be convenient for larger invoices, but they are less natural for a quick face-to-face purchase. They may also require the customer to leave the payment flow, open a banking app, and prove that the transfer was completed. A card-reader workflow is better suited to an immediate exchange, provided the transaction confirmation is clear. For small businesses, the choice is less about finding one perfect method and more about matching the method to the setting.
Digital wallets and contactless cards add another reason to consider a phone-based reader. Customers increasingly expect to tap rather than handle cash, but the actual experience still depends on the phone, the payment setup, and the customer’s preferred method. I would test the complete process with a small amount before using it publicly. That trial should include a successful payment, a declined payment, and the way the app communicates the result, because those moments determine whether the workflow feels trustworthy.
The limitations I would take seriously
The first limitation is reliance on the phone itself. If the battery is low, the device is damaged, notifications interrupt the process, or the connection is unreliable, the payment experience can become awkward. A dedicated reader has its own dependencies, but at least it is purpose-built for that single task. With CPOS, the same device may also be used for calls, messages, navigation, photos, and business administration.
The second limitation is scale. A small independent seller may not need a full register, but a larger operation often needs more than card acceptance. Before adopting CPOS, I would ask whether the business needs product catalogs, multiple user accounts, printed receipts, detailed tax reports, inventory synchronization, or advanced refund controls. If the answer is yes to several of those, a broader point-of-sale platform may be a better foundation, with CPOS serving only if it fits neatly into that existing setup.
The third is customer confidence. Some customers will be perfectly comfortable tapping a card on a phone, while others may prefer a dedicated terminal with a clearly separated payment screen. Presentation matters, especially for higher-value services. I would hold the phone steadily, show the amount before the customer taps, and avoid rushing the confirmation. The app can make acceptance possible, but the person using it still determines whether the transaction feels professional.
There is also a learning curve that the short store description does not reveal. The basic idea is simple, but a real business needs a repeatable sequence for starting a sale, checking the amount, confirming completion, handling a failed attempt, and recording the result. I would create that sequence before the first busy day. A few minutes of preparation can prevent the common mistake of assuming that a successful tap automatically means the whole bookkeeping process is finished.
Who should use it
CPOS is a strong candidate for freelancers, pop-up sellers, independent contractors, and small service businesses that want card acceptance without committing to a larger hardware setup. It also suits people who travel between customers and do not want to carry a separate terminal. The free entry point makes it easier to experiment, and the Everyone age classification keeps the app broadly approachable from a store perspective.
I would also recommend considering it for a business that already has an accounting or order system and simply needs a compact way to accept payment in person. In that situation, CPOS does not have to carry the entire operation. It can focus on the face-to-face payment while the wider business process remains elsewhere. That division of responsibilities is often more realistic than expecting one small app to manage every part of a company.
I would be more cautious for restaurants, busy shops, organizations with several employees, or any business that cannot tolerate a short payment interruption. Those users may be better served by a dedicated terminal or a complete point-of-sale package. I would also hesitate if the business operates mainly in places with poor connectivity or if the phone is already essential for other time-sensitive work. The convenience disappears quickly when the payment device is also the only communication and navigation device.
What I would check before depending on it
Before inviting customers to pay, I would verify that the phone meets the app’s minimum operating-system requirement of Android 8.0 or later and that the device behaves reliably during a test transaction. I would then check the payment provider’s commercial terms, the expected confirmation process, and how I will handle receipts and refunds. These checks are more important than simply installing the app because they determine whether CPOS fits the business rather than merely functioning on the phone.
I would also think about privacy and presentation. A work phone is easier to dedicate to payments than a personal phone filled with private messages and unrelated notifications. If I had to use my everyday device, I would enable a focused work routine, keep the screen clean during transactions, and avoid handing the phone over unnecessarily. These are small operational choices, but they make a phone-based payment experience feel much more deliberate.
Finally, I would keep a backup plan for busy periods. That could be another accepted payment method or a second prepared device, depending on the business. The point is not to overbuild a tiny operation; it is to avoid making one phone the single point of failure. CPOS is most useful when its convenience is supported by a modest amount of preparation.
My final view
CPOS succeeds because it targets a real inconvenience: many small businesses need card acceptance, but do not need a large checkout system. Its free app model, compact phone-based approach, and focus on mobile payments make it a sensible option for testing or simplifying in-person sales. I especially like it for independent workers and temporary selling situations where carrying less equipment has a direct everyday benefit.
My recommendation comes with a clear boundary. I would not treat it as an automatic substitute for a complete retail platform or a dedicated terminal in a high-volume environment. The phone’s battery, connection, suitability, and the business’s wider record-keeping process all matter. If I were starting small, working on the move, and prepared with a backup method, I would give CPOS a serious try. If I needed a full register with extensive controls, I would look elsewhere.
With its release on January 17, 2025, CPOS is still a relatively recent option, but its current version shows that it is being maintained as a practical business tool. My overall verdict is positive: CPOS is best when simplicity and mobility matter more than a complete point-of-sale ecosystem. For the right user, turning a phone into a payment reader can remove more hassle than it creates.
CPOS: Tap to Pay Card Reader FAQ
What is CPOS: Tap to Pay Card Reader?
CPOS: Tap to Pay Card Reader is a mobile point-of-sale solution designed to help businesses accept card and contactless payments using a compatible smartphone or tablet. Instead of relying on a traditional card terminal, the app can turn supported devices into a payment acceptance tool. Availability, supported payment methods, and features may vary depending on your country, device, operating system, and CPOS service account.
Can I use CPOS to accept contactless payments without a card reader?
The app is intended to support Tap to Pay functionality, allowing eligible merchants to accept contactless cards and compatible digital wallets directly on a supported device. However, this does not mean every phone will work automatically. You may need an NFC-enabled device, a supported operating-system version, an approved merchant account, and a business verification process before accepting real payments.
Is CPOS: Tap to Pay Card Reader safe for business transactions?
CPOS is designed for commercial payment processing, but users should still review the provider’s security practices, privacy policy, and merchant agreement before signing up. Payment information is generally handled through encrypted processing and industry-standard safeguards rather than stored openly on the phone. Keep your device updated, use a secure screen lock, and avoid installing the app on rooted or compromised devices.
What fees or requirements should I expect when using CPOS?
Using CPOS may involve transaction fees, account or subscription charges, payout conditions, or other costs determined by the service provider and your location. The exact pricing can depend on card type, transaction volume, currency, and business category. Before downloading or activating the service, check the official pricing information and confirm whether identity verification, bank details, tax information, or business documentation are required.
Which devices and payment methods are compatible with CPOS?
Compatibility depends on the specific CPOS release, your Android or iOS version, NFC availability, and the country where your merchant account is registered. The app may support contactless cards and mobile wallets, while traditional magnetic-stripe or chip-and-PIN payments may require additional hardware. Check the official store listing and CPOS documentation before relying on your phone as your only payment terminal.